- You can start an ATM business with $10k, but it realistically funds two machines with a proper float and a reserve, not five.
- Roughly half the money is machines; the other half is cash that sits in cassettes and in transit, which is capital, not an expense.
- Keep about $1,000-$1,500 untouched for repairs, a slow first month and the ACH lag on weekends.
- Sign locations before you order machines, and pick the processor before either, so installs happen in days instead of weeks.
- Judge the plan at day 90 on withdrawals per machine per month, not on the gross cash that passed through.
If you want to start an ATM business with $10k, plan on two machines, not five. About half of the money buys and installs hardware; the other half becomes cash that lives inside the cassettes and in transit back to your bank. Two well-placed machines with a healthy float and a small reserve is a real business. Four machines on the same budget is a cash crunch waiting for the first holiday weekend.
- Where the $10,000 actually goes
- The float math that decides how many machines you can run
- What decides what two machines earn
- The first 90 days, in order
- An illustrative start: Dana’s first two machines
- Finding the two locations that make or break it
- The honest downsides at this budget
- Frequently Asked Questions
Part of our complete guide: best cash flow businesses.
This post is the budget, the float math, and the first 90 days, written for someone who has the money in a savings account today and wants to know exactly where each dollar goes. If you are still deciding between ATMs and other options at this budget, read the best businesses to start with $10k first; this page assumes you have already picked ATMs.
Where the $10,000 actually goes
New operators tend to price the machine and forget everything else. Here is a realistic split for two machines you own and self-load. Hardware prices are ranges from common retail-grade models; your quote will land somewhere inside them.
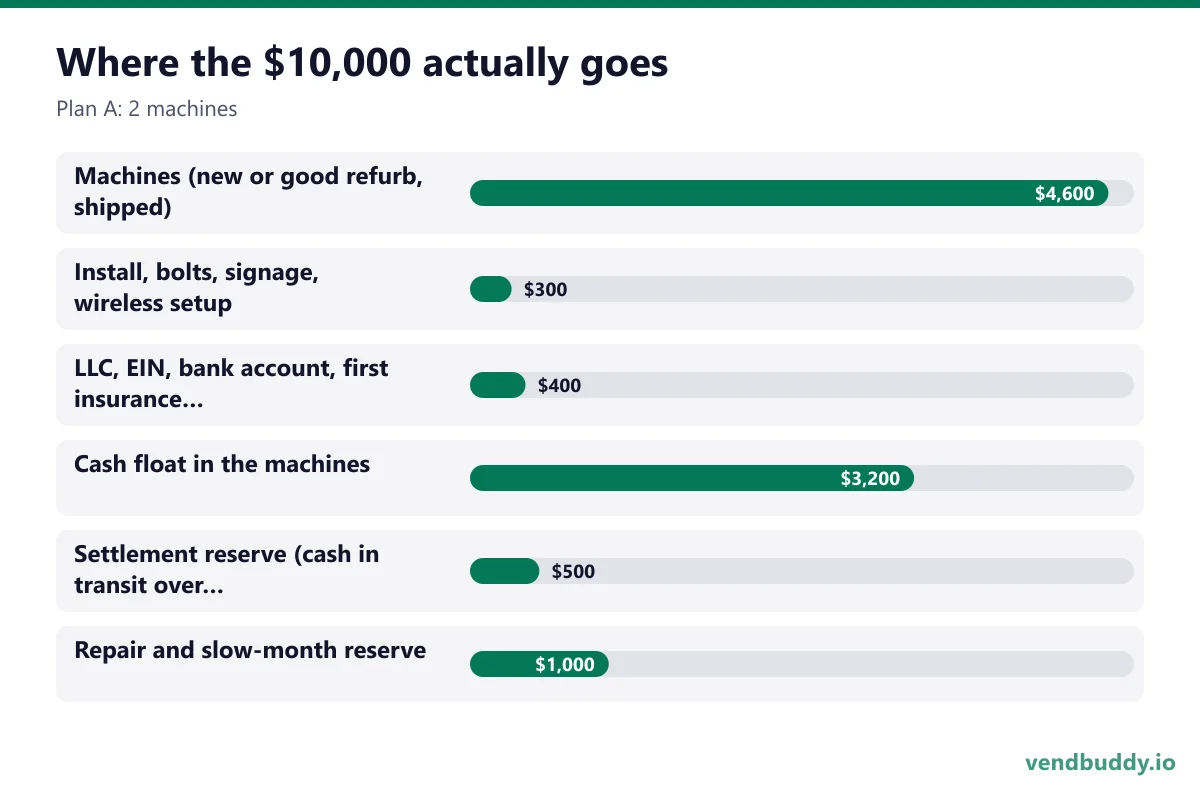
| Line item | Plan A: 2 machines | Plan B: 3 machines |
|---|---|---|
| Machines (new or good refurb, shipped) | $4,600 | $5,700 (refurb) |
| Install, bolts, signage, wireless setup | $300 | $450 |
| LLC, EIN, bank account, first insurance payment | $400 | $400 |
| Cash float in the machines | $3,200 | $3,300 |
| Settlement reserve (cash in transit over weekends) | $500 | $150 |
| Repair and slow-month reserve | $1,000 | $0 |
| Total | $10,000 | $10,000 |
Plan B looks more ambitious and is the one we would talk most people out of. Three machines on $3,300 of float means roughly $1,100 per cassette, which only works if every location is quiet, and quiet locations are exactly the ones that barely cover their wireless bill. It also leaves nothing for a board failure or a location that pulls out in month two. Plan A earns less on paper and survives contact with reality.
For the broader cost picture, including what changes when you add machines five through ten, see our ATM startup cost breakdown.
The float math that decides how many machines you can run
The float is the cash you put in the machine. When a customer pulls $60, your processor collects it from their bank and sends it back to your settlement account, usually the next banking day, along with your surcharge. So the float is never spent, but it is never free either. It is tied up.
A simple way to size it:
Float per machine = withdrawals per day × average withdrawal × days between loads, plus a 25–40% buffer.
At a convenience store doing about 4 withdrawals a day at a $60 average, loaded once a week, that is 4 × $60 × 7 = $1,680, or roughly $2,200 with a buffer. A quiet laundromat at about 1 a day, loaded every two weeks, needs roughly $1,100 with the same buffer. Put those two together and you are at about $3,300, which is why Plan A carries $3,200 plus a $500 settlement reserve for the Friday-to-Tuesday gap.
The lever you control is visit frequency. Load twice a week and you need about half the float. That is the classic trade in this business: capital or time. At $10k you are short on capital, so expect to spend more time. Our full breakdown of that trade, including when third-party vault cash starts to make sense, is in self-load vs third-party vault cash.
Do not fund the float with a credit card
Cash advances carry fees and interest from day one, and a float never pays itself back in a lump. If you want to preserve savings, finance the hardware instead. A 0% intro-APR business card (7 Figures Credit helps people line these up) or a simple everyday card like Chase Freedom Unlimited (a personal card; referral link: we may earn a bonus if you are approved, at no cost to you) used only for the business, for the machine purchase itself, can free up cash for the cassettes, as long as you have a written plan to pay the balance off before the promotional rate ends. If you cannot write that plan down, use cash and run one fewer machine.
See which businesses near you could host a machine
VendBuddy ranks the offices, gyms, apartment buildings and small businesses near you that fit a machine, and shows the best contact on file for each one, so your first call goes to a real place. Searching is free, 5 credits included, no card.
Search my ZIP free →What decides what two machines earn
The gap between a weak ATM and a strong one is almost entirely location. Our ATM income breakdown runs the formula: withdrawals per month times your surcharge, minus the location split and about $80 per machine per month in wireless, processing and a repair reserve. The float is excluded from payback because you get it back if you sell or pull the machines. Judge both machines on their real transaction reports after 90 days.
Compare that to the floor. The same $10,000 in Treasury bills pays roughly $33 to $37 a month with no work, as we lay out in how to invest $10k for cash flow. Two ATMs should beat that by a wide margin, or the extra hours are not worth it.
The first 90 days, in order
The sequence matters more than speed. Most stalled starts ordered machines first and then went looking for somewhere to put them. Writing a two-page ATM business plan before you order anything forces that order: sites first, machines second.
Days 1–14: paperwork and the target list
- Form the LLC, get the EIN, open a business checking account that will act as your settlement account. Keep it separate from personal money from day one; it makes the tax side much simpler (our ATM business tax guide explains why).
- Talk to two or three processors and pick one. It determines which machines you can buy, how fast settlement lands and what you pay per transaction. See how to choose an ATM processor.
- Build a list of 40 to 60 cash-heavy businesses within 20 minutes of home: bars, liquor stores, laundromats, small grocers, barbershops, tattoo shops, bowling alleys. Note which have no ATM or a dead one.
Days 15–45: pitch and sign
- Visit in person at slow hours and ask for the owner. The pitch is short: no cost to them, a share of every surcharge, customers who spend the cash they withdraw inside the store.
- Expect to hear no a lot. Getting two signed placement agreements out of 40 conversations is normal.
- Put the split, term and removal terms in writing. Our placement agreement guide covers what to include.
Days 45–60: order, install, load
- Order machines only after the first agreement is signed. Program them with your processor, bolt them down, test a withdrawal with your own card.
- Load the float, write down the cassette count, and start a simple log: date, count in, count out, cash added.
Days 60–90: measure
- Pull withdrawals per day from the processor portal every week.
- Resize the float to your real numbers instead of estimates. Most operators overload at first.
- Decide on machine three only after both machines have 30 days of real data.
An illustrative start: Dana’s first two machines
Here is an illustrative example (Dana is fictional, and her numbers sit inside the ranges above). Dana had $10,000 saved and a job with Saturdays free. She spent two weekends walking a list of 45 businesses and got two yeses: a corner liquor store and a neighborhood bar with a dead ATM from a previous operator.
The liquor store averaged about 5 withdrawals a day; the bar did 8 on weekends and 2 midweek. She loaded the bar twice a week on Friday and Monday, which kept her float near $3,000 instead of the $4,500 she had budgeted, and she moved the difference into her reserve.
At month six she used the reserve plus what the pair had earned to add a third machine at a laundromat the bar owner introduced her to. That is how routes usually grow: not from the first $10k, but from the first two machines paying for the third.
Finding the two locations that make or break it
At two machines, each location is half your business. A dead placement cannot be averaged out by the other one. The things that move withdrawals are simple: how much the customers pay in cash, and how far it is to the next free ATM.
For a deeper checklist, read the best locations for ATM machines. To build the target list faster, VendBuddy finds bars, laundromats, convenience stores and other cash-heavy businesses in any ZIP and pulls the contact for the person who decides. You can buy credits one pack at a time, so a 50-credit pack for a single ZIP is enough to fill a first pitch list without a subscription.
The honest downsides at this budget
- Cash use is drifting down. Volume at a given location tends to be flat or falling over years, not rising.
- Float scales with every machine. Machine five needs its own float, just like machine one. Vending does not have this problem, which is the main argument in vending vs ATM business.
- You are carrying cash. Vary your loading times, do not load at close with an audience, and keep counting at home or in the office, not in your car. A decent counter helps once you pass a few thousand dollars a week; see our bill counter picks.
- Two machines is a test, not an income. The point of the first $10k is to learn your market’s real numbers cheaply.
If after 90 days both machines are under 60 withdrawals a month, move one before you buy another. Relocation is cheaper than a third bad placement.
Frequently Asked Questions
How many ATMs can I start with if I only have $10,000?
Two is the realistic number if you self-load. Roughly $4,500 to $5,000 goes to machines and install, about $3,000 to $3,500 becomes cash float, and the rest should stay in reserve. Three is possible with refurbished machines and quiet locations, but it leaves no margin for a repair or a slow first month.
Before you buy anything it is worth seeing the alternatives side by side. The machine finder covers used combos through smart coolers, with the caveat that the machine matters far less than the building it stands in.
Is the cash I put in an ATM an expense or an investment?
Neither, strictly. It is working capital that cycles: customers withdraw it, the processor sends it back to your settlement account, and you reload it. You get it back if you pull the machine. It still ties up money that could be earning interest elsewhere, so size it to real withdrawal data.
How long does it take to get a first ATM placed and earning?
Usually two to six weeks from starting the search. Signing the location is the slow part; processor setup and install take days once the agreement is in hand. Operators who order machines before signing a location often wait much longer.
Can I buy ATMs with a business credit card to save my cash?
You can finance the hardware on a 0% intro-APR business card if you have a written plan to pay it off before the promotional rate ends. Do not fund the float with cash advances; fees and interest start immediately. If the payoff plan depends on best-case income, use cash and start with fewer machines.
What should two ATMs make per month when I start?
Quiet placements net little and busy bars far more. The number depends on withdrawals per month, your surcharge and the location split. Judge it after 90 days of real data rather than the first few weeks.
What is selling, which buildings say yes, and the numbers before you buy a machine. Free, confirm from your inbox, unsubscribe in one click. Refer one friend and get 25 VendBuddy credits.
Want the free 26-page Ultimate Vending Guide too? Get the guide
Walk-ins and cold emails find locations. A small site with your own machine photos and a request-a-machine form lets the next one find you. Around machine three to five, an AI builder drafts it in an evening. Wix is the mature site builder; Base44 also builds working tools like a quote form. Start with the AI website walkthrough or Wix vs Base44.
General information, not legal, tax or financial advice. Rules change, so check the official source. Revenue and income figures are examples, not promises. See our terms.