- What an independently placed ATM makes depends on the location's volume; busy nightlife placements do far better, quiet ones barely cover costs.
- Income = withdrawals x (surcharge + ~$0.10-$0.25 interchange), minus the merchant split, wireless, processing and a repair reserve.
- The cash in the machine is your capital cycling back by ACH, not revenue.
- Volume beats hardware: distance to the next ATM and how cash-heavy the customers are decide which end of the range you land on.
- Budget 2-4 hours per machine per month and flat-to-declining volume as cash use drifts down.
How much do ATM machines make? For a small independent operator, the whole answer comes down to one line: withdrawals per month times your surcharge, plus a little interchange, minus the location’s split and your fixed costs.
Part of our complete guide: best cash flow businesses.
Results vary widely by location. Two identical machines can sit ten miles apart and perform completely differently. Below we break the formula into its parts, show how volume differs by location type, show what gets subtracted before anything reaches you, and walk through how operators add machines. If you want the startup budget instead, that lives in our ATM startup cost breakdown; this post is only about the income side.
The formula every ATM runs on
An ATM earns money in two ways, and only one of them is big.
- Surcharge. The fee the customer agrees to on screen before the cash comes out. Independent machines typically charge $2.50 to $3.50. For context, Bankrate’s 2025 fee study put the average surcharge at bank-owned ATMs at a record $3.22, and the cardholder’s own bank adds its own out-of-network fee (about $1.64 on average) on top. That total, roughly $4.86, is what people are used to paying.
- Interchange. A small payment that flows back through the card network on each transaction. After the networks and your processor take their cut, operators commonly see something like $0.10 to $0.25 per withdrawal, and some processing deals keep most of it. Treat it as a rounding bonus, never the plan.
So the monthly gross is simply:
Gross = withdrawals × (surcharge + interchange)
And what you actually keep:
Net = gross − merchant split − wireless − processing fees − repair and insurance reserve
One thing that is not income: the cash in the machine. When a customer pulls out $60, that is your own $60 leaving the cassette. The processor sends it back to your bank account by ACH, usually the next business day, along with the surcharge. Your float is capital that cycles, not revenue. New operators who confuse the two think a machine that dispensed $12,000 last month “did $12,000.” It did $12,000 of volume; the income is only the surcharges and interchange on those withdrawals.
The math by location type
Volume is the variable that swings everything. ATM Depot uses about 5 to 6 transactions a day (150–180 a month) as a planning average; our own ATM placement guide sees quiet laundromats and slow strip malls at 30–80 a month and good bars at 200–500+. To estimate a placement, multiply your own expected withdrawals by your surcharge, subtract the merchant split, then subtract fixed costs: a cellular modem or line (often $15–$35 a month), any processor statement or platform fees, and a reserve for repairs, receipt paper and insurance. Your processor quote supplies the real fees; the structure stays the same.
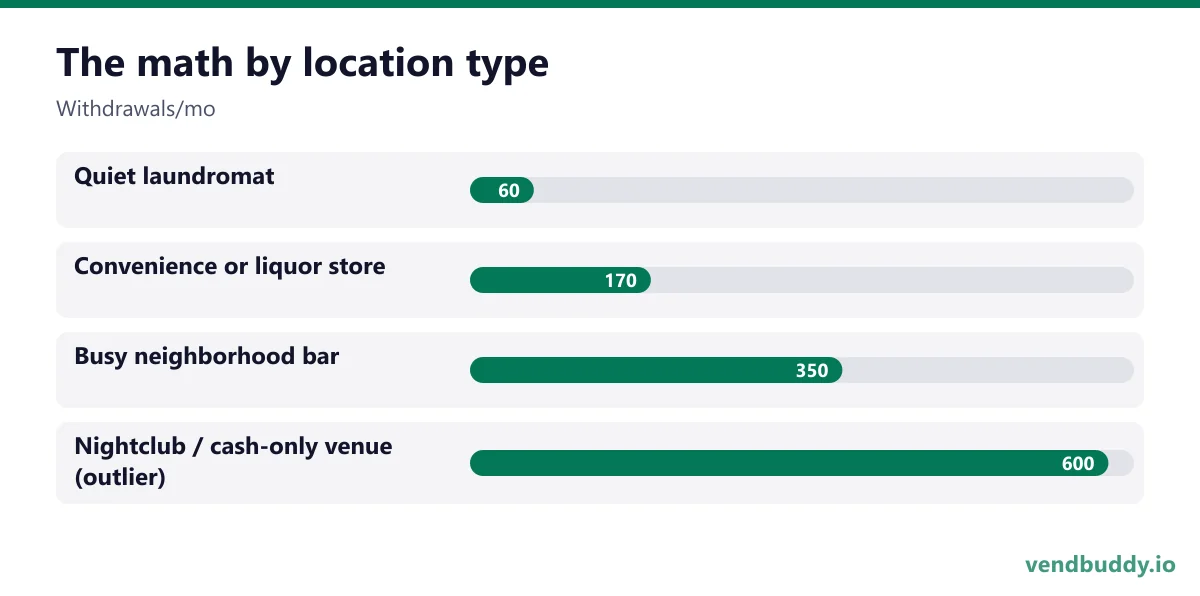
A quiet laundromat machine is often barely worth the drive, a busy bar can carry a portfolio, and the nightclub placements everyone on social media shows you are outliers.
See which businesses near you could host a machine
VendBuddy ranks the offices, gyms, apartment buildings and small businesses near you that fit a machine, and shows the best contact on file for each one, so your first call goes to a real place. Searching is free, 5 credits included, no card.
Search my ZIP free →Five things that move the number more than the machine does
1. Distance to the next ATM
If a bank branch or a surcharge-free network machine sits across the street, your volume gets capped no matter how busy the store is. Customers walk. The best placements are cash-hungry and far from alternatives.
2. How cash-heavy the customers are
Bars with a cash-only pool table, laundromats with coin machines, flea markets, tattoo shops, smoke shops, venues with card minimums. The Federal Reserve’s 2026 Diary of Consumer Payment Choice found consumers still pay cash for about 1 in 7 payments, and roughly three in four carry some cash. The trick is finding the places where that share is far higher than average.
3. The merchant split
Some owners take the ATM as a free amenity. Others want a quarter to half of the surcharge. A 40% split on a $3.00 fee turns $3.00 into $1.80 before your fixed costs. How to structure that conversation is covered in ATM placement agreements and revenue share.
4. Your surcharge
Fifty cents is a 17% raise per transaction at a $3.00 base. Whether volume holds is location-specific; we run the break-even math in how much to charge for an ATM surcharge fee.
5. Uptime
An empty cassette or a dead modem on a Friday night deletes your best 48 hours. Operators who lose money on good locations usually lose it here. How you keep machines full is its own decision: self-load vs third-party vault cash.
What the formula leaves out
Three costs never show up on a processor statement but decide whether the business is worth it.
- The float’s opportunity cost. $3,000 sitting in a cassette earns nothing. In a savings account at roughly 4%, it would earn about $120 a year, around $10 a month. Small per machine; not small at twenty machines.
- Your hours. Loading, balancing, clearing jams and driving. Our cost guide estimates 2–4 hours per machine per month. At ten machines that is a part-time job, even if it is a flexible one.
- A shrinking market. Cash use has been drifting down for years. That does not kill good placements, but it means today’s volume is not a floor. Budget for flat or slowly declining transaction counts, not growth.
How operators add machines
One ATM rarely changes anyone’s life, and every added machine ties up more capital in hardware and float. Operators who grow tend to place machines close together so every reload trip services more than one, judge each placement on its own transaction reports after 60 to 90 days, and move the ones that underperform. Plenty of operators stall at three machines because they cannot find the next good location. Which is why the real work is prospecting, not buying hardware.
The fastest way to test this in your own ZIP is the . Search once, see which businesses sit within a few miles, and reveal five contacts for nothing. It will not tell you who says yes, but it saves the afternoon you would spend building the list by hand.
Where the high-volume placements come from
The busiest placements are found, not stumbled into. The pattern: list every cash-heavy business type in a ZIP (bars, laundromats, convenience and liquor stores, smoke shops, venues), cross off anything next to a bank, then pitch the owner, not the shift manager. Our best ATM locations guide ranks the venue types in detail.
VendBuddy does the listing step for you. It pulls bars, laundromats, convenience stores and venues in any ZIP along with the best contact on file (owner or manager when available), so you spend your time pitching instead of driving around reading signs. Run a search in your area; you can start on the free credits, and if you only need a burst of leads later, credit packs are one-time purchases instead of a subscription.
If you are still deciding between ATMs and a snack route for the same capital, the honest head-to-head is in vending vs ATM business. And if building from zero sounds slow, buying an existing ATM route trades cash for time.
Frequently Asked Questions
How much does one ATM machine make a month on average?
Work it out with the formula: monthly withdrawals times your surcharge, plus a small interchange payment, minus the merchant split and fixed costs like wireless and processing. A common planning figure is 150-180 withdrawals a month, but quiet laundromats see far fewer and strong bars far more. Your location's volume decides the result far more than the machine does.
Do ATM owners make money from the cash that gets withdrawn?
No. The cash a customer withdraws is your own money leaving the machine, and the processor sends it back to your bank account by ACH, usually the next business day. What you earn is the surcharge on each withdrawal plus a small interchange payment. Treat the cash float as capital, not income.
How many transactions does an ATM need to be profitable?
It depends on your surcharge, split and fixed costs, but many operators find that below roughly 50-80 withdrawals a month a machine barely covers wireless, processing and repairs. At 150 or more a month with a modest split, a machine usually earns a meaningful profit. Run the formula with your processor's actual fees before placing.
Is owning ATM machines passive income?
It is low-touch, not hands-off. Self-loading operators spend roughly 2-4 hours per machine per month loading cash, balancing and fixing issues, and empty machines lose their best nights. Paying an armored service for cash delivery reduces your time but costs money per visit.
How much do ATM machines make in bars compared to convenience stores?
Bars and nightlife venues usually see the highest volume, often 200-500 or more withdrawals a month, and customers accept higher surcharges late at night. Convenience and liquor stores tend to run steadier daytime volume at standard fees. Bars also tend to ask for larger merchant splits, so compare net, not gross.
What is selling, which buildings say yes, and the numbers before you buy a machine. Free, confirm from your inbox, unsubscribe in one click. Refer one friend and get 25 VendBuddy credits.
Want the free 26-page Ultimate Vending Guide too? Get the guide
General information, not legal, tax or financial advice. Rules change, so check the official source. Revenue and income figures are examples, not promises. See our terms.