- The trifecta is three Chase cards feeding one points balance. Sapphire plus Freedom Unlimited plus Freedom Flex. The nickname is not official and the arrangement is not clever, it is just three products held together.
- The Sapphire is the hub. It carries the annual fee and it is the account that makes the pooled points transferable to airline and hotel programs.
- Freedom Unlimited does the heavy lifting in vending. Product orders are nobody’s bonus category, so a flat 1.5 per dollar is what most route spend earns.
- Sapphire Preferred is $95 and the Freedoms are $0, and the Sapphire page states a $100 annual Chase Travel hotel credit, so the set is close to free to hold if you book one hotel through Chase Travel a year.
- Against one Bilt card it is closer than it looks. The trifecta earns more on route spend, Bilt earns on the rent payment no Chase card will touch without a fee, and on a typical route the totals land within a few thousand points of each other.
- Do not open three cards in a month while you are about to finance a machine. Fresh inquiries and new accounts are exactly what an equipment lender reads as risk.
The Chase Trifecta is three Chase cards held at the same time so that one pile of points earns at three different rates. A Sapphire card is the hub, a Freedom Unlimited catches everything that is not a bonus category, and a Freedom Flex picks up whatever the quarterly 5% categories happen to be. For a vending operator the honest summary is this: the trifecta earns more per dollar on route spend than a no-fee Bilt card does, and it earns nothing at all on the rent or mortgage payment, which for most operators is the larger number. So the question is not really the earn rate. It is whether you have a housing payment worth earning on. The numbers are below, both ways.
- What the trifecta actually is: three cards, one points pool
- How the points move, and why the Sapphire is the hub
- A vending operator’s version: which card pays for what
- The business version, with an Ink in place of a Freedom
- The math against one Bilt card, honestly
- Setup order and timing
- Frequently Asked Questions
Part of our complete guide: business credit vs personal savings.
Not financial advice. Card terms change, so confirm every fee, rate and benefit on the issuer’s own page before you apply. Figures on this page were checked 2026-09-17 for the Bilt figures and 2026-09-10 for the Chase figures.
What the trifecta actually is: three cards, one points pool
Nobody at Chase calls it a trifecta. It is a cardholder nickname for holding three specific products together, and the reason it caught on is that the three earn in a way that covers almost all consumer spending between them.
Here is what each card stated on its own page when it was read on 2026-09-10.
Chase Sapphire Preferred. $95 annual fee. 5x points on travel purchased through Chase Travel, 3x on dining, 3x on gas stations, EV charging and vacation homes at top brands, 3x on top streaming services and online grocery, 2x on all other travel, and 1x on everything else. Welcome offer stated as 75,000 points after $5,000 of purchases in the first 3 months. No foreign transaction fees. Transfer partners listed include Aer Lingus, Air Canada Aeroplan, British Airways, Flying Blue, Iberia Plus, JetBlue, Singapore Airlines, Southwest, United and Virgin Atlantic on the airline side, and IHG, Marriott Bonvoy, World of Hyatt and Wyndham on the hotel side. The page also states a $100 Chase Travel hotel credit each account anniversary year, a complimentary DoorDash DashPass membership, and a Global Entry, TSA PreCheck or NEXUS application fee credit.
Chase Freedom Unlimited. $0 annual fee. Unlimited 1.5% cash back or more on all purchases, 3% on dining including takeout and eligible delivery, 3% on drugstore purchases, and 5% on travel purchased through Chase Travel. Intro offer stated as a $200 bonus after $500 of purchases in the first 3 months, with 0% intro APR for 15 months on purchases and balance transfers.
Chase Freedom Flex. $0 annual fee. 5% cash back on up to $1,500 of combined purchases in bonus categories each quarter you activate, 5% on travel purchased through Chase Travel, 3% on dining, 3% on drugstores, and 1% on everything else. Same $200 intro bonus after $500 in 3 months, and the same 0% intro APR for 15 months. The 5% has to be activated every quarter, which is the part people forget.
How the points move, and why the Sapphire is the hub
The Freedom cards are marketed in percentages. That framing is what makes the whole arrangement confusing at first, because 1.5% and 1.5 points per dollar are the same thing described two ways. Held on their own, those rewards behave like cash back. Held alongside a Sapphire account, the balance can be pooled there, and from there it can be moved into the airline and hotel programs listed above.
That is the entire mechanic. There is no trick and no loophole. You are paying $95 a year for the option to turn a cash-back balance into a transferable one, plus the Sapphire’s own bonus categories.
Whether that option is worth $95 depends on whether you will ever use it. Transferred points can be worth well more than a penny each on the right award. They can also be worth nothing useful on a Tuesday in July when there are no seats. A cash-back balance is boring and always available. Pick based on which of those describes how you actually book travel, not on which one has better screenshots.
Three cards on a two-machine route is a hobby
Optimizing the earn rate is worth about a hundred dollars a year. One more good placement is worth a few thousand. Put in a ZIP and count what scores near you. Searching is free, 5 credits included.
Find placements near me →A vending operator’s version: which card pays for what
Route spend has an awkward shape for a category card. Most of it is one big line item that no issuer treats as special.
- Product runs. Club store, distributor, cash and carry. This is 45 to 55 percent of your sales and a ten-machine route commonly spends $3,000 to $5,000 a month on it. No bonus category covers it. Freedom Unlimited, 1.5 per dollar.
- Fuel. A real cost once you are servicing eight or ten stops. The Sapphire Preferred page states 3x on gas stations and EV charging, so this is one of the few route costs with a genuine bonus rate on it. Sapphire Preferred, 3x.
- Machines. $1,200 to $3,000 used, $3,000 to $6,500 new. Again no category. Freedom Unlimited, 1.5 per dollar, unless the quarter happens to include a retailer you are buying through, in which case Flex at 5% up to the $1,500 quarterly cap is better for that slice.
- Card readers and telemetry. About $300 a machine plus the monthly fee. Freedom Unlimited.
- Ads and software. If you run ads to find locations, that is a business expense with no consumer bonus category behind it. This is the point where an Ink card starts to make more sense than a Freedom.
Notice how little of a route lands in a bonus category. That is not a flaw in the trifecta, it is a description of the business. Vending is a flat-rate business, and flat-rate businesses reward flat-rate cards.
The business version, with an Ink in place of a Freedom
The same idea works with a business card doing the everyday earning. Keep a Sapphire as the transfer hub and swap one Freedom for a business card or credit line, so route spend sits on a business account instead of a personal one (7Figures Funding (affiliate link) lets you pre-qualify for 0% intro business cards and lines of credit without a hard pull). Two reasons to care, neither about points:
- Reporting. Most issuers report business card activity only to the business bureaus unless the account goes delinquent, so a $6,000 product month does not spike your personal utilization the same week a lender is pulling your file.
- Bookkeeping. One account that only ever sees business charges is worth an hour a month at tax time, and it is what makes the deductions in LLC setup and tax deductions straightforward to substantiate.
Chase publishes several Ink products, a flat-rate no-annual-fee one and category versions with a fee. Their rates change often enough that quoting them here would be worse than useless. Compare the flat rate against the categories your route actually spends in, and remember a category card pays you for spending you do not do. The walkthrough is in the business card guide for vending.
Three cards on a two-machine route is a hobby. Put in a ZIP, see which businesses near you actually score, and get the next placement first. Searching is free and every account starts with 5 credits.
The math against one Bilt card, honestly
Take the route year used across this cluster: $36,000 of product, $8,000 of machines, $1,200 of card readers and $3,000 of fuel. That is $48,200 of spend. Then add the line the trifecta cannot touch at all, which is rent at $1,800 a month, or $21,600 a year.
On the trifecta: $45,200 of the route spend is non-bonus spend on Freedom Unlimited at 1.5, which is 67,800 points. The $3,000 of fuel earns 3x on the Sapphire Preferred, which is 9,000. Rent earns nothing, or costs 2.5 to 3 percent if you push it through a third-party portal. Total roughly 76,800 points against $95 of annual fees.
On one Bilt Blue: the route spend earns 1X, which is 48,200 points, and the rent earns up to 1.25X with no transaction fee, which is 27,000. Total roughly 75,200 points against no annual fee at all.
Referral link: if you’re approved, we earn Bilt points at no cost to you. Bilt sets approval, rates and terms; this isn’t financial advice.
Which is close enough to be a coin toss on points, and not close at all on everything around them. The trifecta costs $95 and needs three applications, three accounts and a quarterly activation you have to remember. Bilt Blue costs nothing and needs one. On this route year the trifecta earns about 1,600 more points, worth roughly $16 at a penny each, which is not a reason to hold two extra cards.
Where the trifecta genuinely wins is a big route and a small rent. Freedom Unlimited pays 1.5 on non-bonus spend against Bilt Blue’s 1X, so every extra $10,000 of annual route spend is 5,000 points in the trifecta’s favour. An operator running $6,000 a month of product from a paid-off house should hold the Chase set and ignore the rent argument entirely.
Where Bilt wins is the opposite and more common case: a modest route, a real rent payment, and no appetite for managing three accounts. Rent at $2,500 a month is 37,500 points a year on its own, which no Chase card earns at any rate, because none of them will process a housing payment without a fee.
So the split is narrower than it looks. The trifecta wins for the operator with a large route, no housing payment to earn on, and the patience to activate the Flex every quarter. Bilt wins for everyone still paying rent or a mortgage. The three-way version, including the business-card side, is in Bilt vs Chase Ink vs Chase Freedom.
Setup order and timing
The order matters more than the cards, and the timing matters more than either.
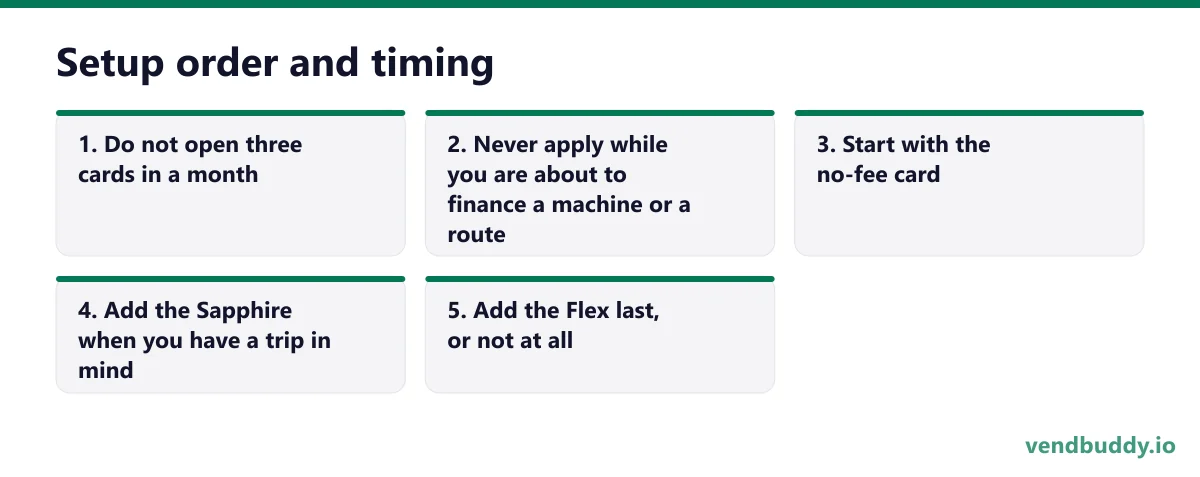
- Do not open three cards in a month. Chase does not publish an application limit, but cardholders widely report declines when too many new accounts have been opened across all issuers in the previous couple of years. Space them out.
- Never apply while you are about to finance a machine or a route. Hard inquiries and new accounts read as instability to an equipment lender, and a vending loan is not worth losing over a $200 sign-up bonus. Get the financing first, compared in the financing guide. If approvals are the hard part, 7 Figures Funding sequences applications across issuers.
- Start with the no-fee card. A Freedom costs nothing to hold and nothing to be wrong about. If the plan falls apart after one card, you have lost no money.
- Add the Sapphire when you have a trip in mind. The $95 is only worth paying when the transfer option gets used, and a card sitting in a drawer transfers nothing.
- Add the Flex last, or not at all. Its value is entirely conditional on activating a category four times a year. Most people are not that person.
One more habit that costs nothing. Pay every one of these in full, monthly. A 5% category earns $75 on the $1,500 quarterly cap. One month of carried interest on a $5,000 balance takes more than that back. No card arrangement survives revolving a balance.
Frequently Asked Questions
What is the Chase Trifecta?
It is three Chase cards held at once so that one points balance earns at three different rates. The usual set is a Sapphire card, either Preferred or Reserve, plus the Freedom Unlimited and the Freedom Flex. The two Freedom cards carry no annual fee and earn what Chase markets as cash back. The Sapphire carries an annual fee and is the account those points get pooled into, which is what makes them transferable to airline and hotel partners. Nothing about the arrangement is official. It is a nickname for a way of holding three ordinary products.
Do you need all three cards for the Chase Trifecta to work?
No, and plenty of people run two. The Sapphire is the one you cannot skip, because it is the account that gives points somewhere to go beyond a statement credit. Freedom Unlimited is the workhorse for spend that falls in no bonus category, which in vending is most of it. Freedom Flex is the optional third card, and it is optional precisely because its 5% categories rotate every quarter and have to be activated. If you will not remember to activate, it earns 1% and you have a card you do not use.
What does the Chase Sapphire Preferred cost and earn?
Read on 2026-09-10, the Sapphire Preferred page states a $95 annual fee, 5x points on travel purchased through Chase Travel, 3x on dining, 3x on gas stations, EV charging and vacation homes at top brands, 3x on top streaming services and online grocery, 2x on all other travel, and 1x on everything else. It also stated a welcome offer of 75,000 points after $5,000 of purchases in the first 3 months, no foreign transaction fees, a $100 Chase Travel hotel credit each account anniversary year, a complimentary DoorDash DashPass membership, and a Global Entry, TSA PreCheck or NEXUS application fee credit. Offers move, so confirm on the issuer page.
Is the Chase Trifecta better than one Bilt card for a vending business?
It depends on whether you pay rent. On route spend alone the trifecta wins, because product earns 1.5 per dollar on Freedom Unlimited against 1 per dollar on Bilt Blue. Bilt earns on a line the trifecta cannot reach at all: per its card page, up to 1.25X on rent or a mortgage with no transaction fee, which on $1,800 a month is 27,000 points a year. Add that in and the two land within a few thousand points of each other on a typical route, except that Bilt Blue has no annual fee, needs one application instead of three, and has no quarterly activation to forget.
How many Chase cards can you open at once?
Chase does not publish an application limit on the card pages, but it is widely reported by cardholders that applications get declined when too many new accounts from any issuer have been opened in the previous two years. Treat three applications in one month as a bad idea regardless. Every application is a hard inquiry, a stack of fresh inquiries is exactly what an equipment lender flags, and the sensible spacing is one card, then several months, then the next.
Can you put vending product on a personal Freedom card?
You can, and lots of operators do before they have a business card. The trade is bookkeeping and credit reporting. Personal card balances count against your personal utilization every month, which matters if you have a machine loan or a mortgage coming. A business card usually reports only to the business bureaus unless the account goes bad. If the plan is to keep scaling, move route spend onto a business card and let the personal trifecta cards handle travel, dining and fuel.
What is selling, which buildings say yes, and the numbers before you buy a machine. Free, confirm from your inbox, unsubscribe in one click. Refer one friend and get 25 VendBuddy credits.
General information, not legal, tax or financial advice. Rules change, so check the official source. Revenue and income figures are examples, not promises. See our terms.