Most new operators don't think about insurance until a property manager asks for a certificate of coverage before they'll allow a machine on-site. At that point, scrambling to get covered costs time and kills placements. Here is exactly what you need, what it costs, and which carriers write policies for vending operators without making you jump through hoops.
- Why insurance is not optional
- General liability: the non-negotiable baseline
- Commercial property coverage
- Workers' compensation: when you need it
- Commercial auto and hired/non-owned auto
- What it costs: 2026 rate ranges
- The carriers that actually write vending operator policies
- Handling COI requests from property managers
Part of our complete guide: starting a vending machine business.
Why insurance is not optional
Two reasons. First, most commercial property managers — especially in healthcare, corporate offices, and managed apartment complexes — require proof of general liability insurance before they will sign a placement agreement. They want to know that if your machine injures a customer or damages their property, they are not exposed. You will lose placements to operators who have coverage if you don't.
Second, your personal assets are at risk without it. An LLC limits liability in theory; in practice, if a customer chokes on a product that vended improperly and your LLC has no assets and no insurance, the plaintiff's attorney will come after the structure directly. A $1M general liability policy that costs $400–$700 per year is cheap protection against a claim that could otherwise reach six figures.
General liability: the non-negotiable baseline
Every vending operator needs a Commercial General Liability (CGL) policy. Standard coverage requested by property managers:
- $1,000,000 per occurrence — the maximum paid for any single claim
- $2,000,000 aggregate — the maximum paid across all claims in the policy year
These limits are industry standard. If a placement agreement specifies different limits, it will almost always be higher than $1M/$2M, not lower. A few high-end corporate clients and healthcare systems require $2M/$4M. Build to $1M/$2M first and upgrade the specific policy when a location requires it.
What CGL covers for vending operators:
- Bodily injury to a customer caused by the machine (crushing injury from tipping, illness from a product, allergic reaction)
- Property damage caused by your machine (water leak from a refrigerated unit damaging flooring, machine falling and denting a wall)
- Personal and advertising injury (less relevant for vending but included in standard CGL)
- Legal defense costs (often the most valuable benefit — the carrier pays to defend you even if the claim has no merit)
What CGL does not cover:
- Damage to your own machines (that is commercial property coverage)
- Employee injuries (that is workers' compensation)
- Your vehicle used for route service (that is commercial auto or hired/non-owned auto)
- Product recall costs (requires a separate product recall endorsement, not needed for most operators)
See which businesses near you could host a machine
VendBuddy ranks the offices, gyms, apartment buildings and small businesses near you that fit a machine, and shows the best contact on file for each one, so your first call goes to a real place. Searching is free, 5 credits included, no card.
Search my ZIP free →Commercial property coverage
A general liability policy does not cover your machines. If a machine is vandalized, stolen, or damaged by fire, flood, or accident, you need commercial property coverage.
Important nuance for vending operators: Standard commercial property policies are written for fixed locations. Vending machines that move between placements are considered "inland marine" property in insurance terminology. Make sure your policy covers equipment at multiple off-premises locations, not just a single business address.
Coverage options:
- Blanket equipment floater: Covers all machines up to a total value, regardless of location. Best for operators with 5+ machines. Typical cost: $150–$350/year for $20,000–$50,000 in coverage.
- Scheduled equipment endorsement: Lists each machine individually with its value. More precise but requires updating whenever you buy or sell machines.
- Bundled BOP (Business Owner's Policy): Some carriers offer a Business Owner's Policy that combines CGL + commercial property + inland marine in one package. This is often the most cost-efficient option for operators with 3–15 machines.
Workers' compensation: when you need it
If you are a solo operator with no employees, workers' compensation is generally not required (requirements vary by state — check your state's rules). The moment you hire even a part-time stocker, workers' comp becomes mandatory in most states and non-negotiable regardless of state requirements.
Workers' comp covers medical expenses and lost wages if an employee is injured on the job — driving the route, unloading product, servicing a machine. The liability exposure without it is severe: an injured employee can sue your LLC personally in many states if coverage was legally required and absent.
Cost: typically $800–$2,000/year for a solo hire in a light commercial/delivery role, depending on state and payroll amount. This cost is fully tax-deductible as a business expense. See the full deductions guide for more.
Commercial auto and hired/non-owned auto
If you drive your personal vehicle on the route, your personal auto insurance policy almost certainly does not cover accidents during business use. This is a significant gap most operators ignore until it is too late.
- Commercial auto policy: If the vehicle is primarily used for the business (dedicated route truck or van), a commercial auto policy is appropriate. Cost: $1,200–$2,400/year depending on vehicle, driver history, and state.
- Hired and non-owned auto (HNOA) endorsement: If you use a personal vehicle part-time for the route, an HNOA endorsement on your CGL policy extends liability coverage to business use without requiring a full commercial auto policy. Cost: $100–$300/year. This is the right move for most early-stage operators who are not yet running a dedicated route vehicle.
What it costs: 2026 rate ranges
Based on actual policy rates from Hiscox, Next Insurance, and Thimble for small vending operators:
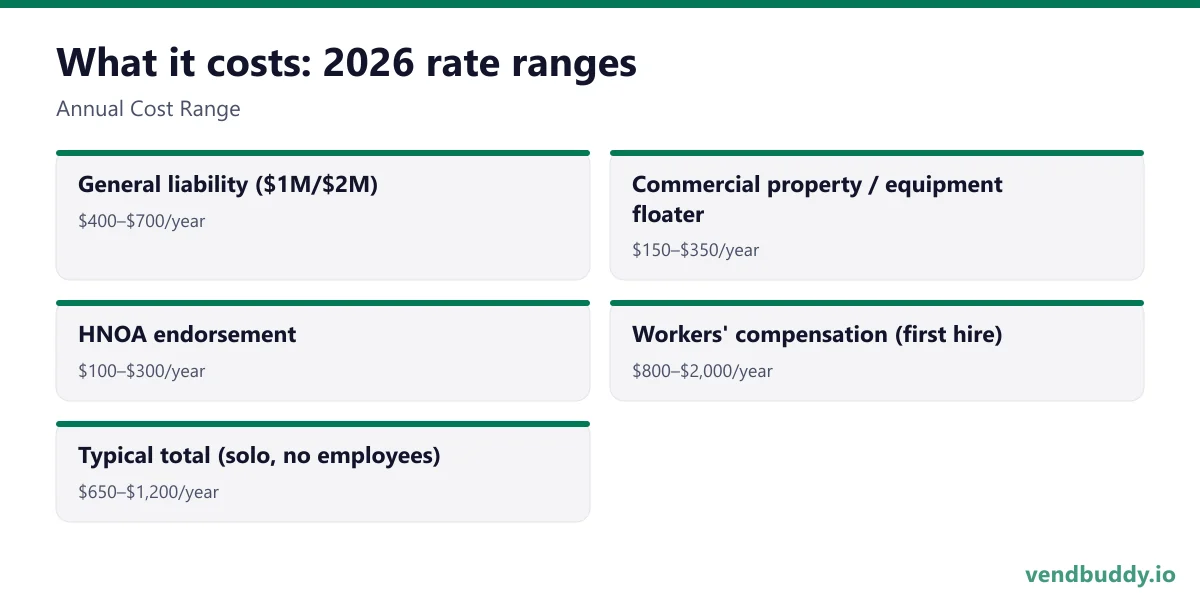
| Coverage | Annual Cost Range | Notes |
|---|---|---|
| General liability ($1M/$2M) | $400–$700/year | Most operators land near $500 |
| Commercial property / equipment floater | $150–$350/year | Depends on total equipment value |
| HNOA endorsement | $100–$300/year | Add to CGL for personal vehicle use |
| Workers' compensation (first hire) | $800–$2,000/year | State-dependent; required upon first hire |
| Typical total (solo, no employees) | $650–$1,200/year | CGL + property + HNOA |
The $400–$1,200/year range you'll see quoted for "vending machine insurance" reflects this combination. Do not try to run a route without at least CGL + HNOA. The cost of a single uninsured claim can exceed $50,000.
The carriers that actually write vending operator policies
Three carriers dominate the small business/vending operator market and will write coverage online in under 20 minutes:
- Hiscox: Strongest name recognition with property managers. A Hiscox certificate of insurance (COI) is rarely questioned. CGL starts around $450/year for solo operators. Has equipment coverage options. Get quotes at hiscox.com/business-insurance.
- Next Insurance: The fastest online quote-to-bind experience. Certificate of insurance generates instantly. Prices are competitive with Hiscox — sometimes lower for operators with a clean claims history. Strong mobile app for COI management.
- Thimble: Offers monthly and annual policies. Monthly policies are useful if you're testing the business before committing to an annual premium. Pay-per-month structure lets you cancel if you exit the business without a penalty. Rates are slightly higher per-year than annual policies but offer flexibility for new operators.
Practical tip: Get quotes from all three before buying. Rates vary 15–25% for the same coverage. The process takes about 30 minutes total and the savings compound over years.
Handling COI requests from property managers
When a property manager asks for proof of insurance, they want a Certificate of Insurance (COI) — a one-page document generated by your carrier that lists your coverage, limits, and policy dates. All three carriers above generate this instantly from their online portal.
Some property managers will ask to be added as an "Additional Insured" on your policy. This means their business is named on your policy and can make claims against it if your machine causes damage to their property. It is a standard, reasonable request. Adding an additional insured is free with most carriers and can be done through the same portal that generates the COI. Budget 5 minutes to do it before your first site visit.
Related: complete startup checklist, LLC formation and what to deduct, negotiating with property managers, full cost breakdown including insurance, and how placement location affects revenue. Use VendBuddy to manage location contracts and track which sites require insurance certificates on file.
What is selling, which buildings say yes, and the numbers before you buy a machine. Free, confirm from your inbox, unsubscribe in one click. Refer one friend and get 25 VendBuddy credits.
Want the free 38-page Ultimate Vending Guide too? Get the guide
Every operator we talk to wants fewer cold calls. The ones who get there have a Google Business Profile and a simple site a manager can check before replying. AI builders make that an evening job now. Wix is the mature site builder; Base44 also builds working tools like a quote form. Start with the AI website walkthrough or Wix vs Base44.
General information, not legal, tax or financial advice. Rules change, so check the official source. Revenue and income figures are examples, not promises. See our terms.